Average Retirement Income for Canadian Teachers
 by Mark Briggs - November 2024
How much retirement income does a Canadian teacher actually receive?
There isn't a single national statistic that answers that question. Teacher retirement income varies considerably depending on the province, years of service, retirement age, pension formula, CPP contribution history, personal savings, and whether the teacher has a spouse or other household income.
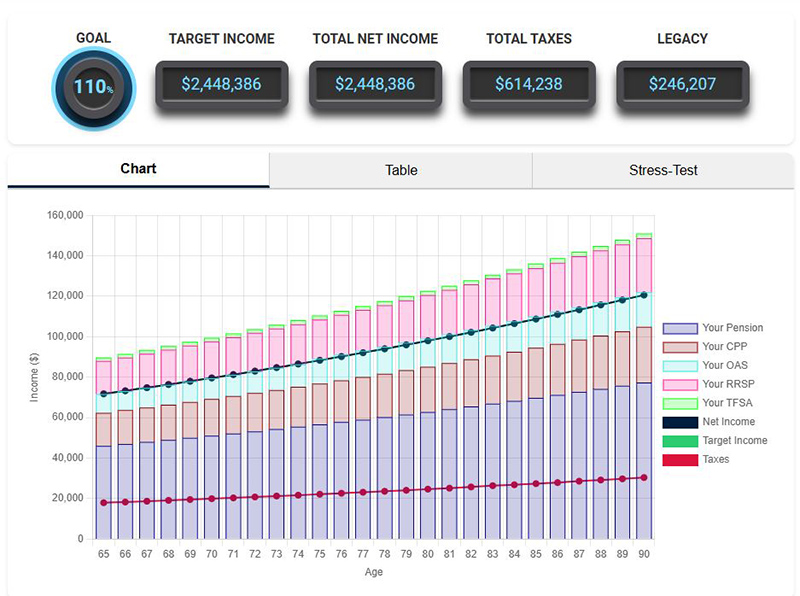
This article originally estimated that a retired Canadian teacher could receive approximately $69,500 per year after tax. That figure should not be interpreted as the average income of all retired Canadian teachers. Instead, it is better understood as an illustrative Retirementize scenario based on a set of assumptions about pension income, CPP, OAS, RRSPs, TFSAs, investment returns, taxes, and retirement age.
Let's look at where an estimate like this comes from—and why the actual number can be very different from one teacher to another.
Sources of Retirement Income for Canadian Teachers
A retired Canadian teacher may have several sources of retirement income, including a defined benefit pension, CPP, OAS, RRSPs, TFSAs, and other personal investments.
The mix is particularly important for teachers because many participate in defined benefit pension plans. A DB pension can provide a substantial lifetime income based primarily on salary and years of pensionable service, reducing the amount of retirement income that must come from personal investments.
Teacher's Defined Benefit Pension
The teacher pension is usually the largest component of retirement income in a typical teacher-retirement scenario.
The actual amount depends on the province and pension plan, as well as the teacher's salary, years of service, retirement age, and pension formula. For example, Ontario Teachers' Pension Plan reported an average starting pension of about $50,000 in 2024, with an average retirement age of approximately 59. :contentReference[oaicite:0]{index=0}
That provides a useful real-world reference point, but it should not be treated as the average pension for every Canadian teacher. Pension structures differ across Canada, and individual pensions can be substantially higher or lower.
Teacher's CPP
CPP is another important source of retirement income, but a teacher's CPP benefit is not automatically the maximum CPP benefit.
CPP is based on an individual's contribution history, pensionable earnings, and the age at which the pension begins. In 2024, the maximum new CPP retirement pension at age 65 was $1,364.60 per month, while the average monthly CPP retirement pension paid during the fiscal year was considerably lower, at $680.18. :contentReference[oaicite:1]{index=1}
A teacher with a long career of relatively high pensionable earnings may receive a CPP benefit well above the average, but it is not appropriate to assume that every teacher receives the maximum.
The timing of CPP also matters. CPP can begin as early as age 60, while delaying it increases the monthly benefit up to age 70. :contentReference[oaicite:2]{index=2}
Teacher's OAS
A teacher who meets the residence requirements for Old Age Security may also receive OAS beginning at age 65 or later.
The maximum OAS pension for someone aged 65 to 74 was $727.67 per month in late 2024. At age 75 and older, the maximum was $800.44 per month. :contentReference[oaicite:3]{index=3}
The actual OAS amount depends on eligibility and years of residence in Canada. Higher-income retirees may also have some or all of their OAS recovered through the OAS recovery tax.
Teacher's RRSP
RRSP savings can provide an important supplement to a teacher's pension, particularly for expenses that fall outside the pension income itself.
However, there is no reliable national statistic that says the average retired Canadian teacher has a particular RRSP balance at age 65. RRSP ownership and balances vary substantially by income, age, province, household circumstances, and years of saving.
Statistics Canada data illustrates this variation. Among Canadian tax filers aged 55 to 64 who contributed to an RRSP in 2023, the median contribution was $5,000. That figure is a contribution statistic—not an account balance—but it demonstrates why it is difficult to construct a national "average teacher RRSP" from contribution data alone. :contentReference[oaicite:4]{index=4}
For our Retirementize example, an assumed RRSP balance can still be useful for demonstrating how personal savings might supplement a teacher's pension.
Teacher's TFSA
TFSAs can also play an important role in retirement because withdrawals are generally not taxable income and do not directly reduce OAS or GIS in the same way taxable registered-account withdrawals can.
Again, however, there is no single "average teacher TFSA balance" that can be applied across Canada.
Statistics Canada reported that 7.5 million Canadian tax filers contributed to a TFSA in 2023, with a median contribution of $6,500 among contributors. For people aged 55 to 64, the median TFSA contribution was also $6,500. :contentReference[oaicite:5]{index=5}
Those numbers are useful for understanding savings behaviour, but they should not be confused with the average TFSA balance of retired teachers.
Teacher Pension Bridge Benefits
One feature that can make teacher retirement income look particularly generous before age 65 is the pension bridge benefit.
For example, Ontario Teachers' Pension Plan provides a bridge benefit for eligible members who retire before 65. The bridge is designed to supplement the lifetime pension until age 65, when the member becomes eligible for an unreduced CPP pension. The bridge ends the month after the member turns 65. :contentReference[oaicite:6]{index=6}
This is important when comparing retirement income at different ages. A teacher might receive significantly more pension income at age 60 than at age 66, even though their overall retirement plan may be working exactly as designed.
Other Assumptions
To create an illustrative retirement-income scenario, we need to make several assumptions. For the Retirementize example, we can assume:
- The teacher retires at approximately age 65.
- The teacher is single.
- The teacher has a substantial defined benefit pension.
- The teacher receives CPP and OAS based on their individual eligibility and contribution history.
- The teacher has some RRSP and TFSA savings in addition to the pension.
- Investment returns continue during retirement.
- Inflation continues to affect future spending and income.
- The retirement plan is evaluated through approximately age 90.
- The teacher's retirement spending is planned rather than simply based on a fixed percentage of their final salary.
These assumptions are important because changing just one of them can substantially change the amount of sustainable retirement income.
The Retirementize Estimate
Using the Retirementize retirement income calculator, we can combine the different sources of income and apply Canadian taxes and retirement assumptions to create an individual retirement scenario.
The original version of this article produced an estimated retirement income of approximately $69,500 per year after tax for the scenario being modelled.
That result is useful as an example, but it should not be interpreted as a national average for Canadian teachers. A teacher with a longer career, higher pensionable salary, larger personal savings, or a different retirement age could have considerably more income. Another teacher with fewer years of service or less personal savings could have considerably less.
The same principle applies geographically. A pension amount that is typical for one provincial plan may not be representative of another province.
Fun Facts
- Ontario Teachers' Pension Plan reported an average retirement age of about 59 in 2024 and an average starting pension of approximately $50,000. :contentReference[oaicite:7]{index=7}
- Ontario Teachers' pensioners can receive a bridge benefit before age 65, which ends after the member turns 65. :contentReference[oaicite:8]{index=8}
- CPP is not a flat retirement benefit. The amount depends on how much and how long a person contributed and when they start receiving it. :contentReference[oaicite:9]{index=9}
- In 2024, the maximum new CPP retirement pension at age 65 was $1,364.60 per month, while the average monthly retirement pension during the fiscal year was $680.18. :contentReference[oaicite:10]{index=10}
- OAS can be delayed beyond age 65. Deferring OAS increases the monthly pension by 0.6% for every month of delay, up to age 70. :contentReference[oaicite:11]{index=11}
- Teacher pensions are generally designed around a formula rather than a fixed account balance, which is one reason defined benefit pensions can provide predictable lifetime income.
Why Your Retirement Income Could Be Very Different
Comparing yourself with an "average" retired teacher can be interesting, but it isn't a substitute for building your own retirement plan.
Consider two teachers who earn similar salaries. One might retire at 58 with 30 years of pensionable service and a substantial TFSA and RRSP. Another might retire at 65 with fewer years of service but larger personal investments. Their retirement-income profiles could look completely different.
Other factors matter too:
- Province and pension plan
- Years of pensionable service
- Highest or final average salary
- Retirement age
- CPP start date
- OAS start date
- RRSP and TFSA balances
- Home ownership and mortgage costs
- Taxes
- Healthcare and long-term-care costs
- Marital or household status
- Desired retirement lifestyle
Don't Focus Only on the Average
The most important lesson from this exercise is that retirement planning is personal.
A teacher with a strong defined benefit pension may be in an excellent position for retirement, but that doesn't necessarily mean they can spend a particular amount every year. Housing costs, taxes, travel, healthcare, family support, and other expenses can dramatically change the amount of income required.
Likewise, a teacher with a smaller pension isn't necessarily at risk. A paid-off home, significant TFSA savings, part-time work, or other assets can make up for a lower pension.
Conclusion
Canadian teachers are often in a strong retirement position because many participate in defined benefit pension plans that provide predictable lifetime income.
But there is no single "average retirement income" that accurately describes every Canadian teacher. Pension benefits differ by province and individual circumstances, while CPP, OAS, RRSPs, TFSAs, taxes, and spending needs can all change the final result.
The original Retirementize example produced approximately $69,500 of after-tax annual retirement income under a particular set of assumptions. Rather than treating that number as a national average, use it as a starting point for thinking about what your own retirement might look like.