
Can I Retire with $2 Million?
 by Mark Briggs - November 2025
If you have $2 million saved and are wondering, “Can I retire with $2 million?”, the answer depends on more than the size of your nest egg. Your age, spending needs, taxes, investment returns, inflation, Social Security benefits, and where you live can all have a significant effect on how long your money lasts.
To illustrate the difference, we used Retirementize to model the same basic retirement scenario in two different states: California and Florida. The original Retirementize projections used approximately $106,000 of annual after-tax income in California and $112,000 in Florida. The examples show why taxes and other location-specific costs can matter when deciding where to spend your retirement years.
Setting the Stage: The Retirement Scenario
Before comparing the two states, let's establish the assumptions used in the Retirementize examples. The original scenario assumes:
- Age 67 at retirement, an important age for Social Security planning.
- A nest egg of $2,000,000 in a 401(k), meaning withdrawals are generally taxable as ordinary income.
- Social Security income of approximately $1,976 per month in the original model.
- An expected lifespan through age 90, providing 23 years of retirement planning.
- Annual inflation of approximately 2.1%.
- Investment growth of approximately 4% annually.
These are modeling assumptions rather than guarantees. A different investment return, inflation rate, retirement age, spending level, tax situation, or longevity assumption could produce a very different result.
For context, the Social Security Administration reported that the average monthly benefit for a retired worker was $1,978.77 in January 2025. That makes the original $1,976 assumption reasonably close to the national average, although an individual's actual benefit depends on their earnings history and claiming age.
Retirementize can be used to model different combinations of savings, income, taxes, investment returns, inflation, and retirement assumptions.
Example 1: Retiring in California
California can be an expensive state in which to retire, particularly for households with substantial taxable income. California does not tax Social Security benefits, but distributions from traditional retirement accounts such as a 401(k) can be subject to California income tax.
That distinction is important. The state treatment of Social Security is different from the treatment of taxable retirement-account withdrawals. A retiree receiving most of their income from a traditional 401(k) therefore needs to account for both federal and California income taxes.
In the original Retirementize example, the $2 million scenario produced approximately $106,000 per year of after-tax income through age 90.
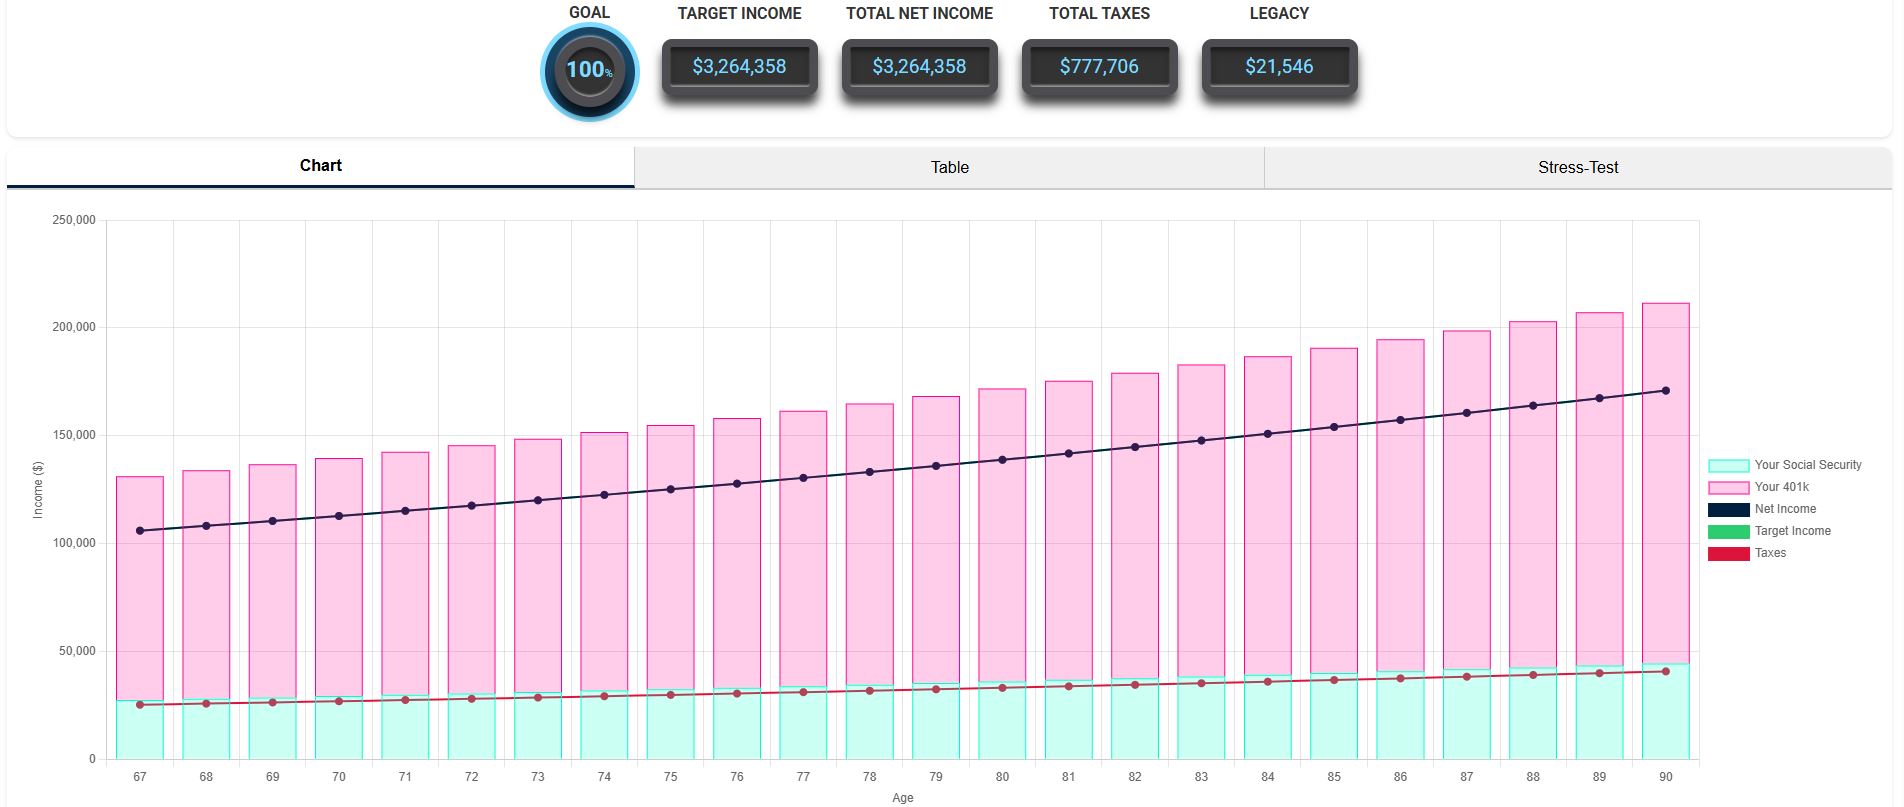
At roughly $106,000 per year, the modeled income represents about $8,833 per month before considering how actual spending changes from year to year. Whether that is enough depends heavily on housing, healthcare, travel, family support, debt, and lifestyle choices.
California's tax treatment is only one part of the equation. Property taxes, housing costs, insurance, healthcare, and other living expenses can also influence how far a retirement portfolio goes.
Example 2: Retiring in Florida
Florida takes a different approach to individual income taxation. Florida does not impose a personal state income tax. That means a Florida resident does not pay Florida individual income tax on withdrawals from a traditional 401(k).
Federal income taxes still apply, however. Moving to Florida does not make a traditional 401(k) tax-free; it simply removes the state individual income tax that would otherwise apply.
In the original Retirementize scenario, the same $2 million portfolio produced approximately $112,000 per year of after-tax income in Florida.
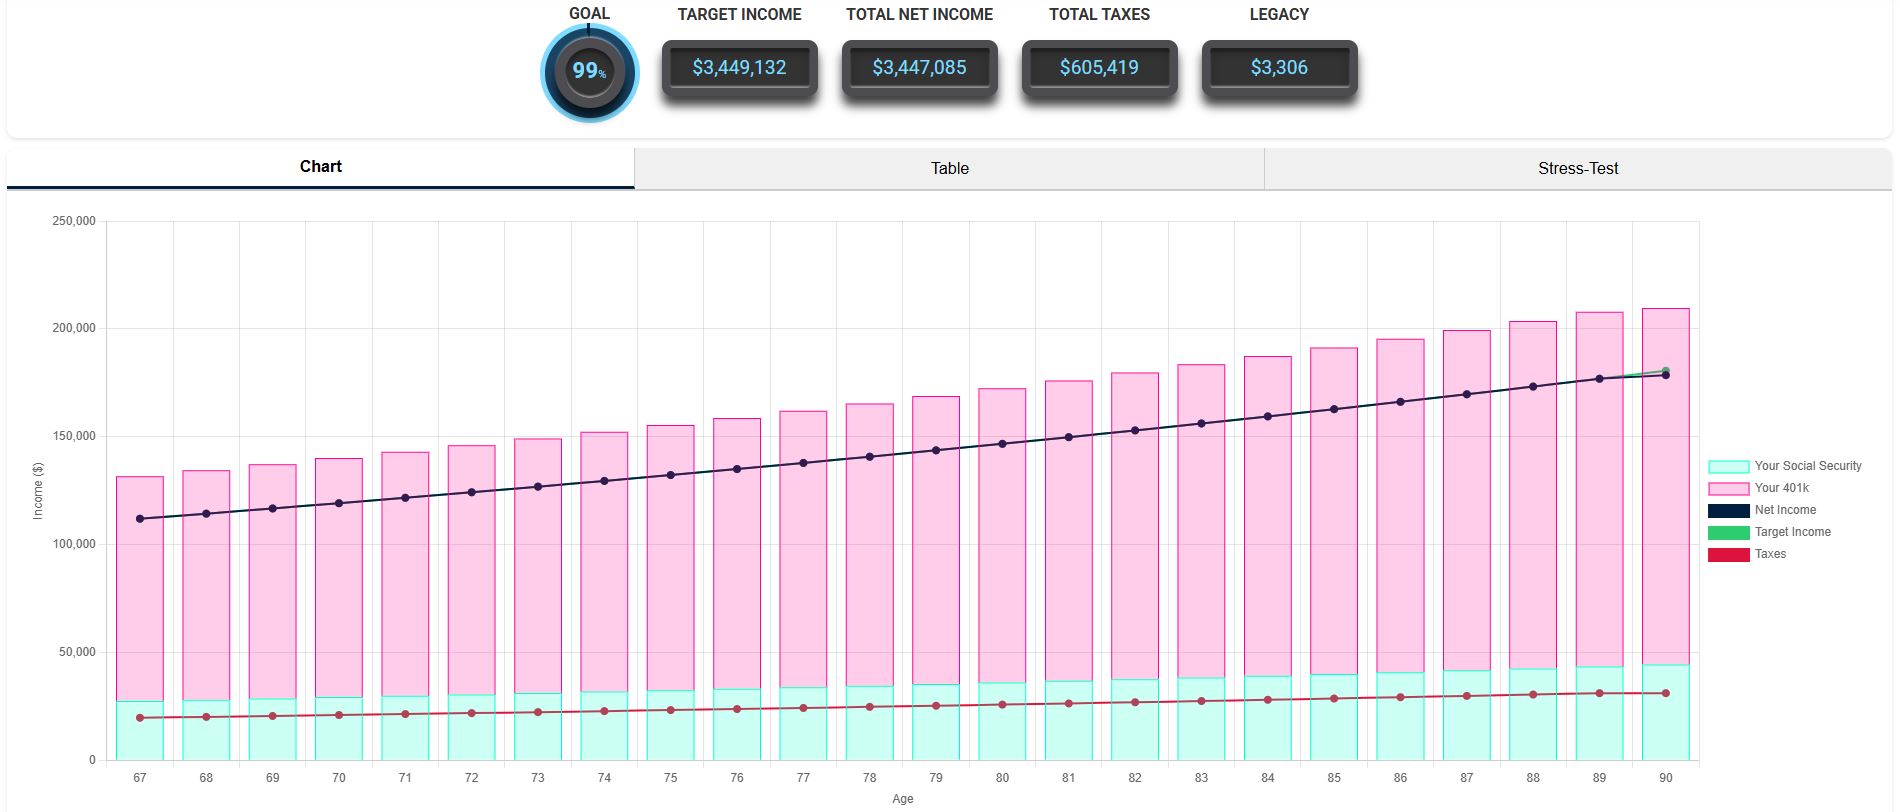
That is approximately $6,000 more annual after-tax income than the original California scenario. Over 23 years, the difference would amount to roughly $138,000 if the annual difference remained constant. Actual results would not necessarily follow that simple calculation, because taxes, investment returns, inflation, spending, and portfolio withdrawals change over time.
Comparing California and Florida
Here is the comparison from the original Retirementize projections:
| State | After-Tax Annual Income | Total Income (Age 67–90) | Total Taxes (Age 67–90) |
|---|---|---|---|
| California | $106,000 | $3.26 million | $778,000 |
| Florida | $112,000 | $3.45 million | $605,000 |
The important point is not that one state will always produce a particular retirement income. These figures come from a specific Retirementize scenario and its assumptions. Change the retirement age, investment return, inflation rate, spending target, Social Security benefit, or tax situation and the results can change substantially.
The comparison does demonstrate how state income taxes can affect after-tax retirement income when a large portion of a portfolio is held in tax-deferred accounts.
Taxes Are Only One Piece of the Puzzle
It can be tempting to look at a state with no individual income tax and assume it will automatically be cheaper to retire there. That isn't necessarily the case.
Before moving, retirees should also consider:
- Housing costs: Home prices, rents, property taxes, and maintenance can vary considerably.
- Insurance: Homeowners, flood, auto, and other insurance costs can materially affect a retirement budget.
- Healthcare: Premiums, deductibles, prescriptions, and out-of-pocket expenses can vary by individual and location.
- Transportation: Car ownership and commuting requirements can change significantly after retirement.
- Family considerations: Living closer to children, grandchildren, or other family members can have value that isn't captured by a tax calculation.
- Estate and property considerations: State laws and local housing markets may affect long-term planning.
In other words, the lowest-tax location isn't necessarily the lowest-cost location. A complete retirement plan should consider the entire household budget rather than focusing on one tax rate.
What This Means for Your Retirement Planning
So, is $2 million enough to retire? For some households, it can be. For others, it may not be. The answer depends on how much you need to spend, how long you need the money to last, and how your investments and other income sources perform.
A few important considerations stand out:
- Taxes matter: A large traditional 401(k) balance can create substantial taxable income as withdrawals are made. Modeling federal and state taxes can provide a more realistic picture of retirement spending power.
- Social Security matters: Social Security can provide an important base of guaranteed income, but the amount varies significantly from person to person.
- Inflation matters: $100,000 of spending power today will not have the same purchasing power decades from now. Retirement plans need to account for rising expenses.
- Investment returns matter: A 4% assumed return is a modeling assumption, not a guarantee. Actual markets can perform much better or much worse from year to year.
- Healthcare matters: Healthcare costs can be significant even after Medicare begins. Fidelity's 2026 estimate puts average lifetime healthcare and medical expenses for a 65-year-old retiring in 2026 at approximately $185,500 for an individual, excluding long-term care.
- Lifestyle matters: A retiree who spends $60,000 per year has a very different retirement plan from someone who spends $120,000 or more.
- Longevity matters: Planning only to age 80 or 85 can produce a very different result from planning into the 90s or beyond.
If you are considering a move in retirement, compare the complete financial picture rather than simply comparing state income-tax rates. You can also explore our articles on state income taxes and affordable states to retire in .
Fun Facts
- The Federal Reserve's Survey of Consumer Finances has historically shown that average retirement-account balances for households ages 65–74 are far below $2 million. One commonly cited figure from the Federal Reserve data is approximately $426,000, illustrating how a $2 million retirement portfolio is substantially above the average.
- The Social Security Administration reported an average monthly benefit of $1,978.77 for retired workers in January 2025.
- Florida has no personal state income tax, although residents still pay federal income taxes and other state and local taxes.
- California does not tax U.S. Social Security benefits at the state level, even though some Social Security benefits can be taxable on a federal return.
- Fidelity's 2026 estimate says a 65-year-old retiring in 2026 may spend approximately $185,500 on healthcare and medical expenses throughout retirement, excluding long-term care.
Conclusion
So, can you retire with $2 million? It can be enough for many people, but the answer is highly personal.
A $2 million portfolio combined with Social Security can provide a substantial source of retirement income. But the amount you can sustainably spend depends on factors such as your age, desired lifestyle, investment performance, inflation, taxes, healthcare expenses, and how long you live.
The California-versus-Florida comparison also demonstrates why after-tax income can be more useful than simply looking at a portfolio balance. Two people can start retirement with the same $2 million and have different amounts available to spend depending on their tax situation and other expenses.
Your retirement success isn't simply about reaching a particular savings number. It's about understanding how your savings, income, taxes, investments, and spending work together over time.
That's what the Retirementize retirement calculator is designed to help you explore. Enter your own assumptions and see how changes to retirement age, spending, investments, taxes, and location can affect your projected retirement income.
