
Canadian Retirement Without Savings
 by Mark Briggs - March 2025
Retirement is a phase many people look forward to—a time to relax, pursue passions, and enjoy the fruits of years of work. But what if you are approaching retirement without substantial personal savings?
The situation can feel overwhelming, but having little or no retirement savings does not necessarily mean you have no retirement income. In Canada, government programs such as the Canada Pension Plan (CPP), Old Age Security (OAS), and the Guaranteed Income Supplement (GIS) can provide an important foundation for people with limited resources.
However, government benefits alone may provide only a modest standard of living. Your housing costs, province, health, family situation, work income, and eligibility for government benefits can make a significant difference.
Let's look at what a retirement without significant savings could look like and what strategies can help make it more manageable.
Government Benefits Can Provide a Retirement Income Foundation
Canada's retirement income system has several government programs designed to provide income to seniors. The amount you receive depends on your circumstances, including your CPP contribution history, age, marital status, income, and years of residence in Canada.
Canada Pension Plan (CPP)
The Canada Pension Plan (CPP) is a contributory retirement pension. If you have worked and contributed to CPP, you may be eligible to receive a monthly pension starting as early as age 60.
The standard age to start CPP is 65, but you can choose to begin between ages 60 and 70. Starting before 65 permanently reduces the monthly pension by 0.6% for every month before 65, up to a maximum reduction of 36% at age 60. Delaying CPP after 65 increases the pension by 0.7% for every month of delay, up to a maximum increase of 42% at age 70.
For someone with limited savings, the decision about when to start CPP can be particularly important because CPP is paid for life. There is no single starting age that is right for everyone; health, cash-flow needs, other income, and life expectancy all matter.
Example: If your calculated CPP pension at age 65 were $1,000 per month, starting at 60 would reduce that amount to approximately $640 per month. Waiting until 70 would increase it to approximately $1,420 per month.
Old Age Security (OAS)
The Old Age Security (OAS) pension is different from CPP. You do not need to have worked or contributed to CPP to receive OAS. Eligibility is primarily based on age and your residence history in Canada.
OAS can normally begin at age 65 and can be delayed as late as age 70. Delaying OAS increases the monthly pension by 0.6% for every month of delay, up to a maximum increase of 36% at age 70.
OAS is also income-tested through the OAS recovery tax. Higher-income seniors may have to repay some or all of their OAS.
For perspective, the maximum OAS pension for someone aged 65 to 74 was $751.97 per month for July to September 2026. Actual payments can be lower depending on eligibility and residence history.
Guaranteed Income Supplement (GIS)
For lower-income seniors, the Guaranteed Income Supplement (GIS) can be extremely important.
GIS is a monthly benefit available to eligible low-income OAS recipients. The amount depends on income and marital status. Unlike CPP and OAS, GIS is specifically designed to provide additional support to seniors with lower incomes.
As an illustration of the scale of the benefit, the maximum GIS payment for a single OAS recipient was $1,123.17 per month for July to September 2026, although the actual amount depends on income and other circumstances. The income threshold for a single recipient was $22,800 for that period.
This is why a person with little retirement savings should not assume that their retirement income will consist only of CPP and OAS. GIS eligibility can make a substantial difference for lower-income retirees.
The Impact of Retirement Age on Your Income
When you stop working can have a major impact on your financial situation, especially if you have little or no personal savings.
Early Retirement Before 65
Retiring before 65 creates an income gap that needs to be funded somehow.
CPP can begin as early as age 60, but starting early permanently reduces the monthly benefit. OAS and GIS are generally not available until age 65.
That means someone who stops working at 60 may need to rely on CPP, employment income, a spouse's income, housing equity, or other resources for several years before OAS and potentially GIS become available.
Example: If your age-65 CPP entitlement were $1,000 per month, starting at 60 would reduce it to approximately $640 per month. That lower payment would continue for life.
Retirement at 65
Age 65 is an important milestone in the Canadian retirement system because OAS becomes available at that age, assuming you meet the eligibility requirements.
For someone with limited savings, the combination of CPP, OAS and potentially GIS can provide a basic retirement income foundation.
However, the actual amount can vary substantially. CPP depends on your contribution history, OAS depends partly on your Canadian residence history, and GIS depends on your income and family situation.
Delaying Retirement Beyond 65
Working beyond 65 can provide several advantages for someone without significant savings.
You can continue earning employment income, potentially continue contributing to CPP, and delay CPP and/or OAS if doing so fits your circumstances.
Delaying CPP to age 70 can increase the pension by up to 42%, while delaying OAS to age 70 can increase the OAS pension by up to 36%.
However, delaying benefits is not automatically the best choice. Someone with low income and little or no savings may need the benefits earlier, and GIS eligibility can also be an important consideration.
Retirement Example: Age 65 With Little or No Savings
Let's consider a simplified example of a single Canadian who reaches age 65 with very little personal retirement savings.
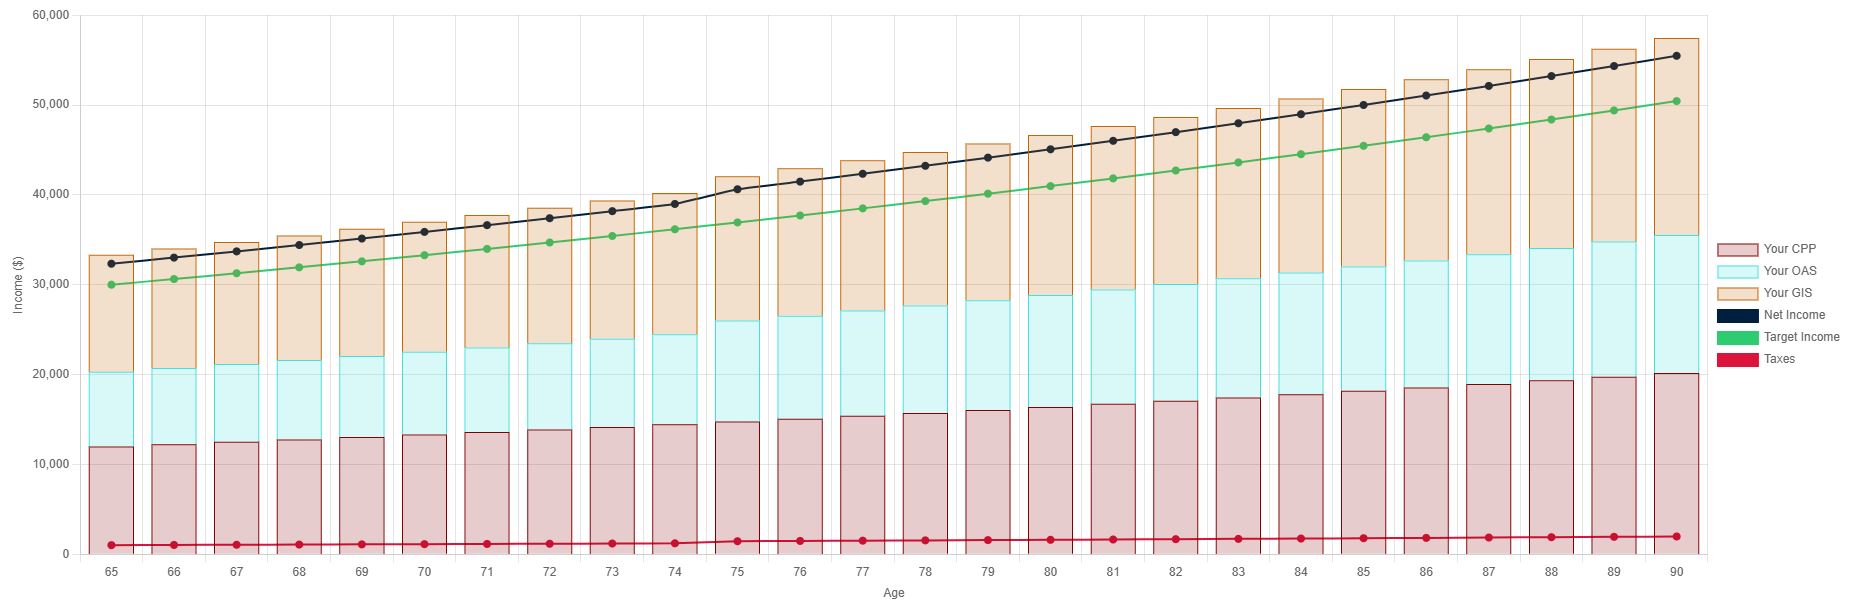
Suppose the person has a CPP pension based on their contribution history, receives OAS, and has little other taxable income. Depending on their income and circumstances, they may also qualify for GIS.
This is an important distinction: there is no single government-benefit amount that applies to everyone who retires without savings. CPP varies based on contribution history, OAS can be partial depending on residence history, and GIS is income-tested.
For that reason, a retirement-income calculator can be much more useful than simply adding today's maximum government benefits together.
Retirementize can model the interaction between CPP, OAS, GIS, taxes, inflation, housing costs, and other sources of retirement income to show how a specific retirement scenario could develop over time.
Where You Live Matters
If you are approaching retirement with limited savings, housing and living costs can be just as important as your government benefits.
A retirement income that works reasonably well in a lower-cost community may be difficult to stretch in a high-cost housing market.
Housing Costs
Housing is often one of the largest expenses in retirement. Someone who owns a mortgage-free home may have a very different financial situation from someone who is renting at market rates.
Downsizing, moving to a lower-cost community, renting out part of a home, or moving in with family are possibilities that some retirees consider when savings are limited.
Healthcare and Other Costs
Canada's public healthcare system provides important coverage, but retirees can still face expenses for prescription drugs, dental care, vision care, mobility equipment, travel, and other services depending on their province and individual circumstances.
When comparing potential retirement locations, look beyond the advertised cost of housing. Transportation, property taxes, utilities, insurance, food and access to healthcare can all affect your actual retirement budget.
Taxes
Provincial and federal income taxes also affect how much of your retirement income you actually keep.
Rather than assuming one province is universally better for retirees, it is more useful to compare your expected income and expenses under the tax and cost-of-living conditions that would apply to your particular situation.
Supplemental Income Sources for a No-Savings Retirement
Government benefits may provide the foundation, but additional income can make a significant difference.
- Part-time work: Even a modest amount of employment income can help pay for groceries, housing or discretionary spending.
- Consulting or freelance work: Previous professional experience can sometimes be turned into flexible retirement income.
- Downsizing: Selling a larger home and moving to a less expensive property may reduce ongoing expenses and potentially release home equity.
- Renting part of your home: Depending on your circumstances, renting a room or secondary space may provide additional income.
- Home equity: Some homeowners consider options such as a home-equity line of credit or reverse mortgage. These products can have significant costs and should be evaluated carefully.
- Government assistance: Depending on your circumstances, benefits such as GIS and provincial programs may provide additional support.
Budgeting for a Frugal but Comfortable Retirement
If you do not have significant savings, your retirement budget becomes particularly important.
Separate Essential and Discretionary Expenses
Start by identifying the expenses you must pay every month: housing, utilities, food, transportation, insurance, medication and other essential costs.
Then identify discretionary expenses such as entertainment, restaurants, hobbies and travel. This makes it easier to understand how much income you actually need.
Look for Low-Cost Activities
Many communities offer free or inexpensive recreation programs, libraries, walking groups, community centres and senior activities. Retirement does not necessarily require a large entertainment budget.
Watch Housing Costs
A retiree receiving government benefits may be able to manage a modest budget when housing costs are low but struggle when a large portion of monthly income goes toward rent or a mortgage.
For someone approaching retirement without savings, housing decisions can therefore be among the most important financial decisions they make.
Fun Facts
- Canada's retirement system includes several layers, including CPP, OAS and GIS. They are designed to work differently and eligibility is not the same for each program.
- CPP can begin as early as age 60 or be delayed until age 70. Starting at 60 results in a permanent reduction of up to 36%, while delaying to 70 can increase the pension by up to 42%.
- OAS can be delayed from age 65 to 70, increasing the monthly pension by up to 36%.
- Statistics Canada reported that 10.3% of retired Canadians aged 55 and older were working after retirement in 2023, up from 7.3% in 2019.
Can You Really Retire in Canada Without Savings?
Yes, it is possible to retire with little or no personal savings, but that does not mean retirement will automatically be comfortable.
For someone in this situation, government benefits may provide a basic foundation. The combination of CPP, OAS and potentially GIS can provide meaningful income, particularly for people with lower incomes.
The challenge is making that income cover your actual expenses.
Housing costs, food, transportation, healthcare, taxes and unexpected expenses all matter. Someone who owns a mortgage-free home and lives modestly may have a very different retirement experience from someone paying high rent in an expensive city.
How Retirementize Can Help
Retirement planning becomes even more important when you do not have a large investment portfolio to fall back on.
The Retirementize Calculator can help you model different retirement scenarios and see how government benefits, taxes, inflation, housing costs and other income sources interact over time.
You can explore scenarios such as:
- Retiring at 60, 65 or 70
- Starting CPP at different ages
- Starting OAS at different ages
- Working part-time during retirement
- Changing your housing costs
- Comparing different retirement budgets
- Understanding how taxes affect your retirement income
- Evaluating how long your retirement income may last
Conclusion
Retiring in Canada without significant personal savings is challenging, but it is not necessarily impossible.
CPP, OAS and GIS can provide an important income foundation for eligible Canadians. Working longer, earning some part-time income, controlling housing costs and creating a realistic budget can further improve the situation.
The key is to understand exactly how much income you can expect and how that compares with your expected expenses. Government benefit amounts and eligibility rules can change, so use current government information when making decisions about your retirement.
If you are approaching retirement with little or no savings, try the Retirementize Retirement Income Calculator to build a personalized retirement-income scenario and see what your options look like.
