
Can You Retire with $1,000,000 in Your RRSP?
 by Grant Marsten - October 2024
Reaching $1,000,000 in your RRSP is a major retirement milestone. But does it mean you can stop working? The short answer is: possibly — but the answer depends on much more than the size of your RRSP.
Your retirement income will depend on your age when you retire, your spending needs, CPP and OAS benefits, investment returns, inflation, taxes, housing costs, healthcare expenses, and how long your money needs to last. A million dollars can support very different lifestyles for different retirees.
There is another important point that is sometimes overlooked: an RRSP balance is pre-tax money. You do not get to spend the entire $1,000,000. Withdrawals from an RRSP or RRIF are generally taxable income, so your after-tax retirement income will be lower than the amount withdrawn.
Is $1,000,000 Enough to Retire in Canada?
There is no universal retirement number that works for everyone. Someone who owns their home, has modest expenses, and receives substantial CPP and OAS may have a very different retirement plan from someone who rents, travels extensively, or wants to leave a large estate.
Before asking whether $1,000,000 is enough, ask a better question: How much after-tax income do I need every year, and how long does that income need to last?
Consider these factors:
- Retirement age: Retiring at 55 requires your portfolio to last much longer than retiring at 70.
- Annual spending: A $50,000 retirement lifestyle is very different from a $100,000 lifestyle.
- CPP: Your CPP benefit depends on your contribution history and the age you start collecting it.
- OAS: OAS can provide an additional source of inflation-adjusted retirement income for eligible Canadians.
- Housing: Mortgage payments, rent, property taxes, maintenance, and downsizing can significantly affect your budget.
- Taxes: RRSP and RRIF withdrawals are generally taxable.
- Inflation: Your retirement expenses may rise substantially over a retirement lasting 30 years or more.
- Investment returns: The order in which good and bad investment years occur can matter just as much as the long-term average.
- Longevity: A retirement plan that works until age 90 may not work if you live to 100.
Example: Retiring at 65 with a $1,000,000 RRSP
Let's look at a simplified example to understand the mechanics.
Suppose a single Ontario resident:
- Retires at age 65
- Has $1,000,000 in an RRSP
- Receives CPP
- Has no defined-benefit workplace pension
- Assumes 2% annual inflation
- Assumes a long-term investment return of 4%
- Wants retirement income to continue through age 95
Under assumptions like these, a retirement income in the range of the original example may be possible. However, it would be misleading to say that every Canadian with $1,000,000 in an RRSP can safely spend $55,000 after tax every year.
The actual answer requires a complete retirement-income calculation that accounts for taxes, government benefits, investment growth, inflation, withdrawals, and the age at which the money is spent.
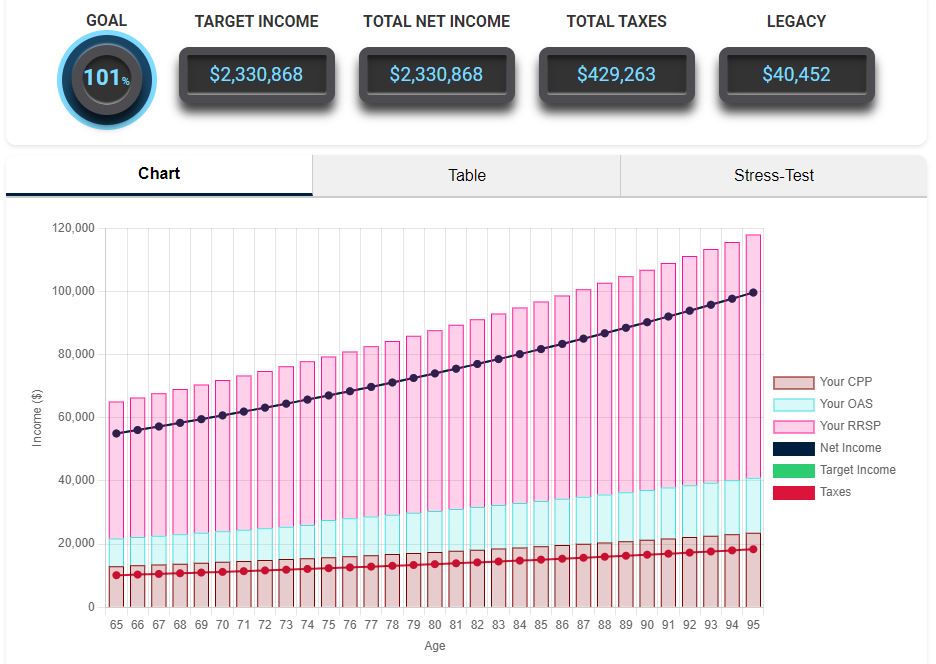
This is why a retirement calculator can be more useful than a simple withdrawal-rate calculation. The objective is not merely to determine how much you can withdraw from the RRSP. It is to determine how much after-tax spending income your entire retirement plan can support.
What About a Couple with $1,000,000 in RRSPs?
A couple can have a different retirement-income picture because two people may receive CPP and potentially two OAS benefits. Household expenses also do not necessarily double when a second person is added to the household.
Consider a simplified couple where the household has $1,000,000 in RRSP assets and both spouses have meaningful CPP benefits. The amount they can sustainably spend will depend on the same factors as the single-person example, plus how their income and withdrawals are divided between the two spouses.
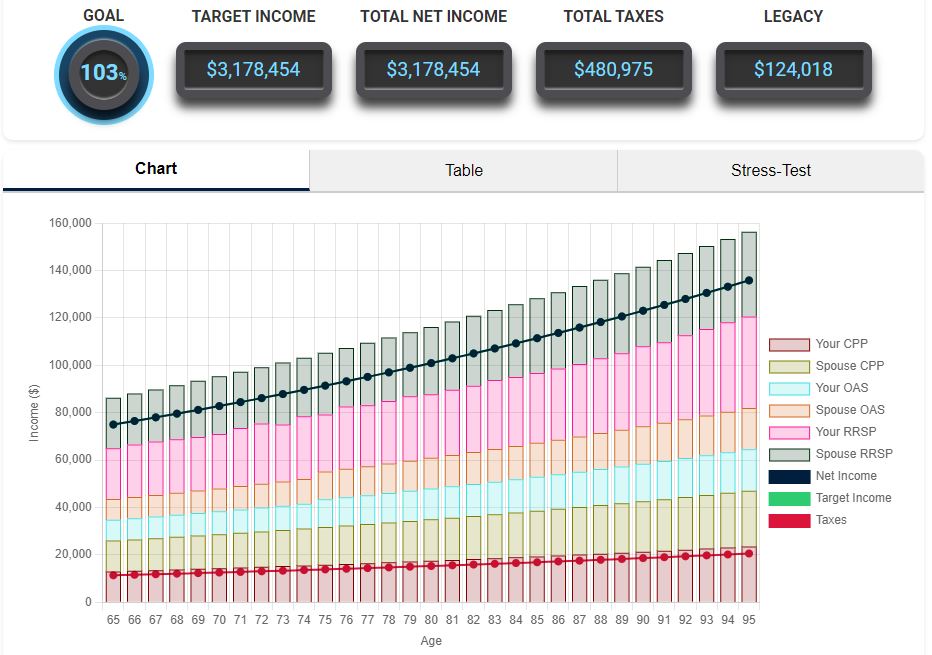
This is also where tax planning becomes particularly important. Two spouses may have opportunities to coordinate RRSP/RRIF withdrawals, CPP timing, OAS timing, and other sources of income.
How Much Income Can $1,000,000 Generate?
One of the most common retirement questions is: "How much can I withdraw from $1 million each year?"
A simple way to illustrate the question is to apply different initial withdrawal rates:
- 3%: $30,000 in the first year
- 4%: $40,000 in the first year
- 5%: $50,000 in the first year
- 6%: $60,000 in the first year
These are illustrations, not guaranteed retirement-income levels. A withdrawal rate does not automatically account for Canadian taxes, CPP, OAS, inflation, investment fees, changing spending, or the sequence of investment returns.
For example, withdrawing $50,000 from a $1,000,000 RRSP does not mean you have $50,000 of spending money. RRSP withdrawals are generally included in taxable income, so the amount available after tax will be lower.
CPP and OAS Can Make a Big Difference
Your RRSP is only one part of your retirement-income picture. Government benefits can provide an important base of income that reduces the amount you need to withdraw from your portfolio.
CPP benefits vary significantly from person to person because they depend on contribution history, earnings, and the age at which CPP begins. In 2026, the maximum new CPP retirement pension at age 65 is $1,507.65 per month, while the average monthly amount for new beneficiaries at age 65 is substantially lower. Your own CPP estimate is more useful than either number.
CPP can begin as early as age 60 or be delayed to age 70. Starting later increases the monthly benefit, so the decision should be considered as part of the overall retirement-income strategy rather than in isolation.
OAS is another potential source of income. Eligible Canadians can begin OAS at 65 or defer it to as late as 70, with higher monthly payments for those who defer.
The key point is simple: don't judge a $1,000,000 RRSP in isolation. Look at your RRSP, CPP, OAS, workplace pensions, TFSA, non-registered investments, real estate, and other income sources together.
How to Build a $1,000,000 RRSP
Getting to $1,000,000 generally requires some combination of time, contributions, investment growth, and tax-efficient saving.
1. Start Early
Time is one of the most powerful tools available to an investor. Contributions made decades before retirement have more time to benefit from compound growth.
2. Contribute Consistently
Your RRSP deduction limit is generally based on unused contribution room plus the lesser of 18% of the previous year's earned income or the annual RRSP dollar limit, with adjustments for pension plans and other factors.
The annual RRSP dollar limit is $33,810 for 2026. Your personal available contribution room may be different, so check your CRA account or notice of assessment before making a contribution.
3. Take Advantage of Employer Matching
If your employer offers a retirement savings program with matching contributions, understand the rules and consider taking full advantage of the available match where appropriate.
4. Give Compounding Time to Work
Here's a simplified illustration: suppose someone begins with $5,000 at age 25, increases annual contributions by 2% each year, and earns an average 6% annual return.
Depending on the exact timing of contributions and compounding assumptions, this type of long-term saving strategy can potentially grow into a seven-figure portfolio by age 65. The important lesson isn't the exact result — investment returns are never guaranteed — but the power of starting early and increasing contributions over time.
For more information, read our article on the retirement savings magic number.
How Should You Invest a $1,000,000 RRSP?
Having $1,000,000 is only part of the equation. How the money is invested can have a major effect on the retirement plan.
Diversification
A diversified portfolio can spread investment exposure across different asset classes and markets. The appropriate mix depends on your time horizon, risk tolerance, income needs, and overall financial situation.
Don't Ignore Sequence-of-Returns Risk
Two retirees can earn the same average investment return over 20 years and experience very different outcomes if their good and bad years occur in a different order.
This is especially important during the first several years of retirement because withdrawals are being made while the portfolio is also experiencing market fluctuations.
Keep Enough Liquidity
Retirement portfolios do not necessarily need to be invested for maximum growth at all times. Having money available for near-term spending can reduce the pressure to sell volatile investments during a market downturn.
For another perspective on retirement withdrawals, see our article on the four percent rule.
RRSP Tax Benefits — and the Tax Bill Later
RRSPs are powerful because contributions can generally be deducted from taxable income, and investment income inside the plan is not taxed as it accrues.
But the tax is generally deferred, not eliminated. Withdrawals from an RRSP are generally taxable income.
This creates an important retirement-planning question: When should you withdraw the money?
Taking too little from an RRSP in the early years of retirement may leave you with a large taxable account later. Taking too much can unnecessarily increase your current tax bill and potentially affect income-tested benefits.
There is no single withdrawal strategy that is correct for every retiree. Your age, other income, tax bracket, CPP/OAS timing, spouse's income, charitable goals, estate objectives, and expected longevity can all matter.
What Happens to Your RRSP at Age 71?
An RRSP must mature by the end of the year in which you turn 71. Common options include transferring the RRSP to a RRIF or using the funds to purchase an eligible annuity.
Once you have a RRIF, annual minimum withdrawals apply. The minimum is based on a prescribed factor and the value of the RRIF at the beginning of the year. You can withdraw more than the minimum, but generally cannot withdraw less.
For a standard RRIF, the prescribed minimum factor is 5.28% at age 71. The percentage increases as you get older.
This is important because the amount you are required to withdraw can eventually become a significant portion of the remaining RRIF balance.
Read more about what a RRIF is and how RRSP withdrawals are taxed.
Inflation: The $1,000,000 Today Won't Buy the Same Amount Tomorrow
Inflation is one of the biggest long-term retirement risks.
If inflation averages 2% for 30 years, prices would roughly double. At 4% inflation, purchasing power erodes much faster.
This means a retirement plan cannot simply assume that $60,000 today will be enough forever. Your spending needs may rise over time, although your spending pattern may also change as you age.
Consider the same couple from our earlier example. If inflation rises significantly above the original assumption, the amount of income required to maintain the same lifestyle also rises.
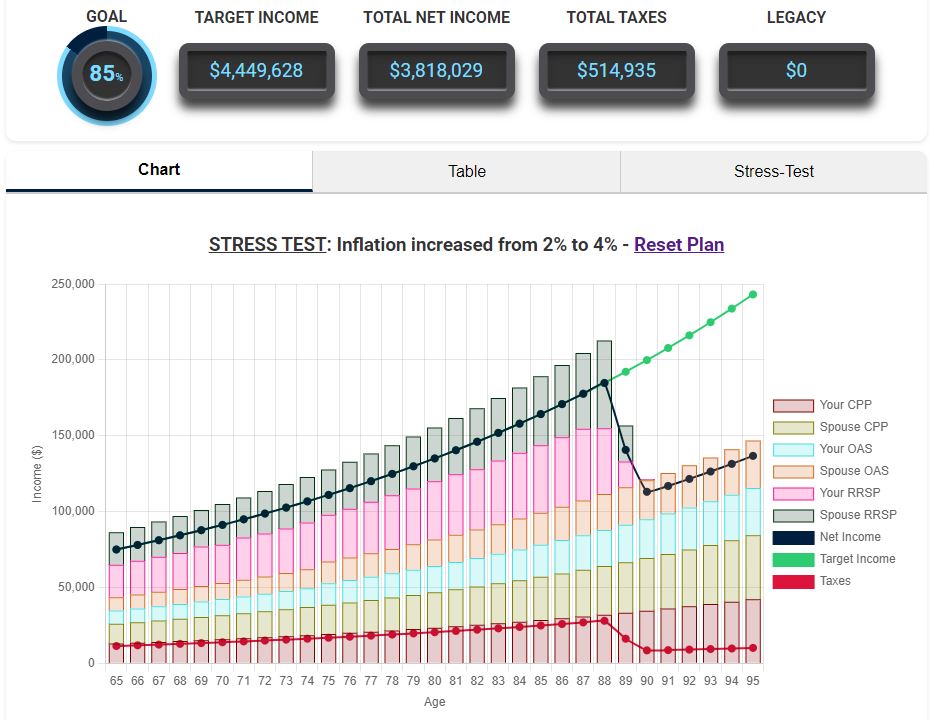
Stress-testing your retirement plan at different inflation rates can reveal how sensitive your plan is to changing economic conditions.
Longevity Risk: What If You Live to 100?
A retirement plan should not be built around your life expectancy alone. If you live longer than expected, your money needs to last longer too.
Someone retiring at 65 should consider what happens if they reach 90, 95, or even 100. This does not mean you need to leave $1,000,000 untouched. It means your withdrawal strategy should be tested against a long retirement horizon.
Consider the couple from our example living five additional years beyond the original age-95 scenario. Their portfolio now has to support another five years of spending, inflation, investment volatility, and potentially higher healthcare and support costs.
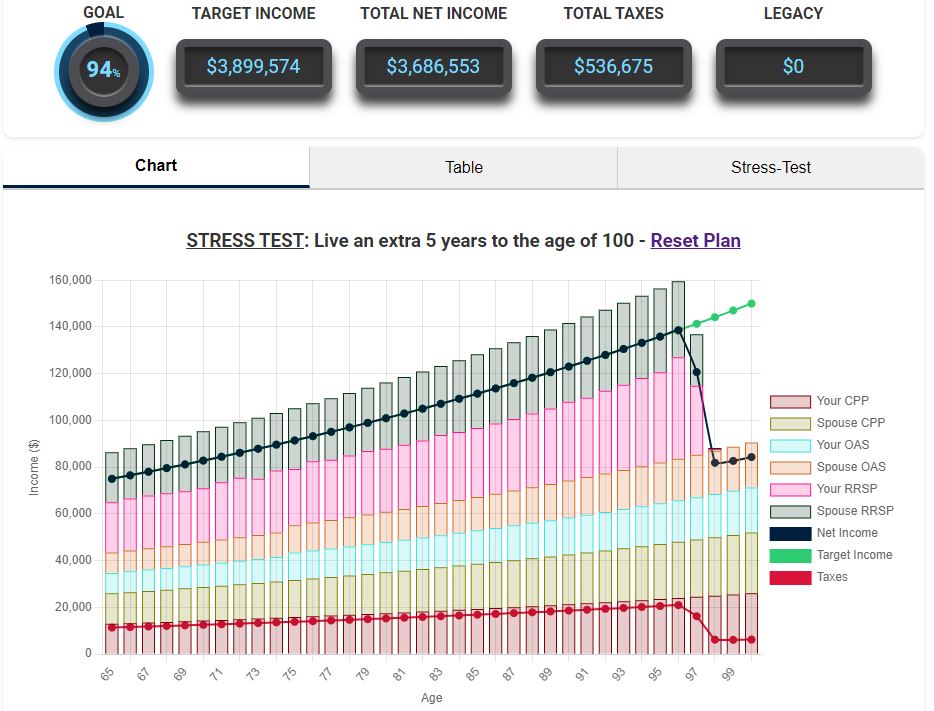
Your Retirement Lifestyle Matters
The amount of money you need in retirement depends heavily on how you intend to live.
Someone who wants to travel several times a year, maintain multiple vehicles, support adult children, pursue expensive hobbies, or maintain a large property may need substantially more income than someone who enjoys a low-cost lifestyle close to home.
Your expenses may also change as you age. Early retirement can be an active period with significant spending on travel and recreation. Later years may involve less travel but potentially greater spending on healthcare, home support, transportation, or assisted living.
That's why a good retirement plan should not assume that your spending will remain exactly the same from age 65 through age 95.
Read more about the importance of retirement budgeting before deciding how much your $1,000,000 portfolio needs to provide.
What If You Have More Than $1,000,000?
Reaching $1,000,000 doesn't mean you should stop planning. In fact, larger RRSP balances can create their own tax-planning challenges.
If you continue contributing and your RRSP grows substantially beyond $1,000,000, future mandatory RRIF withdrawals may become larger as well.
This is one reason retirement planning should include more than investment growth. You may want to coordinate RRSP withdrawals with CPP, OAS, other investment accounts, charitable giving, estate planning, and the tax situation of your spouse.
Don't Forget Your Other Retirement Accounts
A $1,000,000 RRSP is not necessarily better or worse than a retirement portfolio spread across several account types. The tax treatment of each account matters.
Your retirement assets might include:
- RRSPs and RRIFs
- TFSA savings and investments
- Non-registered investments
- Defined-benefit or defined-contribution pensions
- CPP and OAS
- Cash and savings accounts
- Real estate
- Rental income
- Annuities or other guaranteed income
The goal is not necessarily to maximize the balance in one account. The goal is to create a sustainable and tax-efficient retirement-income strategy.
Fun Facts About $1,000,000 RRSPs
- RRSP millionaires are relatively uncommon. Statistics Canada's 2022 data shows that 13,450 tax filers reported RRSP contributions while having incomes of $1,000,000 or more, but income statistics should not be confused with the number of people who have $1,000,000 in RRSP assets.
- RRSP contribution room is tied to earned income. The general formula uses 18% of prior-year earned income, subject to the annual dollar limit and adjustments such as pension adjustments.
- A million-dollar RRSP is not a million dollars of after-tax spending money. RRSP and RRIF withdrawals are generally taxable income.
- CPP isn't automatically the same for everyone. Your CPP retirement pension depends on your contribution history, earnings, and when you start receiving it.
So, Can You Retire with $1,000,000 in Your RRSP?
Yes, $1,000,000 can potentially support a retirement. But the balance by itself cannot tell you whether your retirement plan is sustainable.
A retiree with $1,000,000, substantial CPP and OAS, a paid-off home, modest spending, and a well-designed withdrawal strategy may have a very different outlook from someone with the same $1,000,000 who retires early, carries a mortgage, travels extensively, and needs the portfolio to provide nearly all of their income.
The real question is not: "Do I have $1,000,000?"
It is: "Can my complete retirement-income plan support the lifestyle I want for as long as I live?"
That's where detailed retirement modelling becomes useful. Instead of relying on a single withdrawal percentage, test different retirement ages, spending levels, investment returns, inflation assumptions, CPP and OAS start dates, longevity scenarios, and tax outcomes.
Use the Retirementize retirement income calculator to build your own scenario and see how your retirement income, savings, taxes, and assumptions interact over time.
