
Retirement Calculators Using Income Splitting
 by Mark Briggs - September 2025 (Updated September 2026)
Can income splitting really change your retirement income? It can. For Canadian couples with significantly different retirement incomes, pension income splitting can reduce taxes and increase the amount of money available for household spending.
But there is an important distinction: not every source of retirement income can simply be split between spouses. Canadian pension income splitting rules apply to eligible pension income, while CPP pension sharing is a separate program and OAS generally cannot be split through the CRA's pension income splitting election.
That's why a retirement calculator that models taxes, inflation, government benefits, and different income sources can be much more useful than a simple retirement savings calculator.
Let's look at a real-world Retirementize case study involving a couple in British Columbia. We'll compare their retirement plan with and without pension income splitting and see how the results change.
The Couple's Retirement Setup
Here's the scenario we modeled:
- Both spouses are age 65 and have just retired
- One spouse receives a $50,000 annual pension
- Each spouse receives $15,000 of CPP per year
- Each spouse receives $8,880 of OAS per year
- Target after-tax household income: $90,000 per year
- Inflation assumption: 2.1%
- Province: British Columbia
- Planning horizon: age 65 through age 90
The important feature of this example is that a large portion of the couple's taxable pension income is concentrated in one spouse. That can create an opportunity to shift eligible pension income to the lower-income spouse.
Under Canada's pension income splitting rules, spouses or common-law partners may jointly elect to allocate up to 50% of eligible pension income to the other spouse. The actual tax benefit depends on the couple's complete tax situation, including other income, deductions, credits and government benefits.
What Is Pension Income Splitting?
Pension income splitting allows a Canadian resident who receives eligible pension income to jointly elect with their spouse or common-law partner to allocate up to 50% of that eligible income to the other person for tax purposes.
The election is made jointly for the tax year. The transferring spouse reports the pension income and claims a deduction for the elected split-pension amount, while the receiving spouse reports the allocated amount as pension income.
The purpose isn't to create additional household income. Instead, it changes how eligible income is allocated between the two tax returns. When one spouse has substantially more taxable income than the other, this can sometimes reduce the family's combined income tax.
Not All Retirement Income Can Be Split
This is one of the most important points when using a retirement calculator. The CRA specifically excludes several types of income from pension income splitting, including OAS and CPP/QPP benefits.
Eligible pension income can include certain pension and annuity payments and, when the applicable age and other requirements are met, certain RRIF and RRSP annuity income.
CPP can be shared between spouses under a separate Service Canada program, but CPP pension sharing is not the same thing as the CRA's pension income splitting election.
These distinctions matter because a retirement plan should model each income source according to the rules that actually apply to it rather than assuming that all household income can be divided equally.
Scenario 1: Without Income Splitting
First, we ran the couple's retirement plan without pension income splitting. Retirementize calculates their projected income, taxes, spending and ability to reach their after-tax retirement income target.
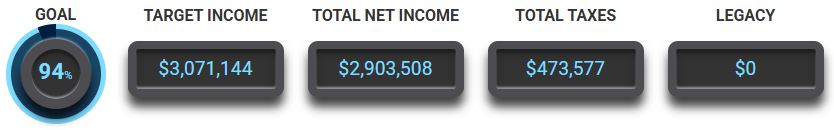
Summary Dashboard — No Splitting
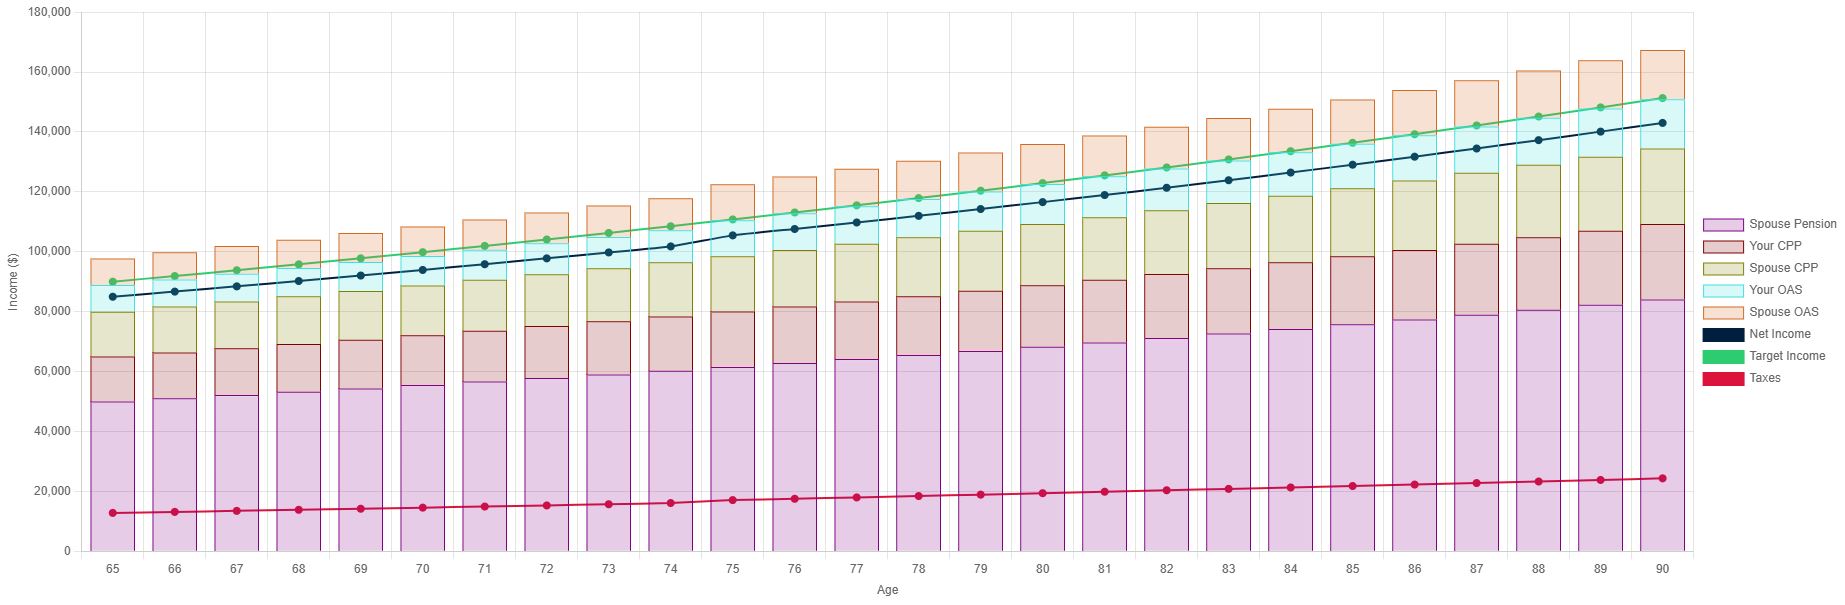
Yearly Income Chart — No Splitting
Detailed Breakdown Table — No Splitting
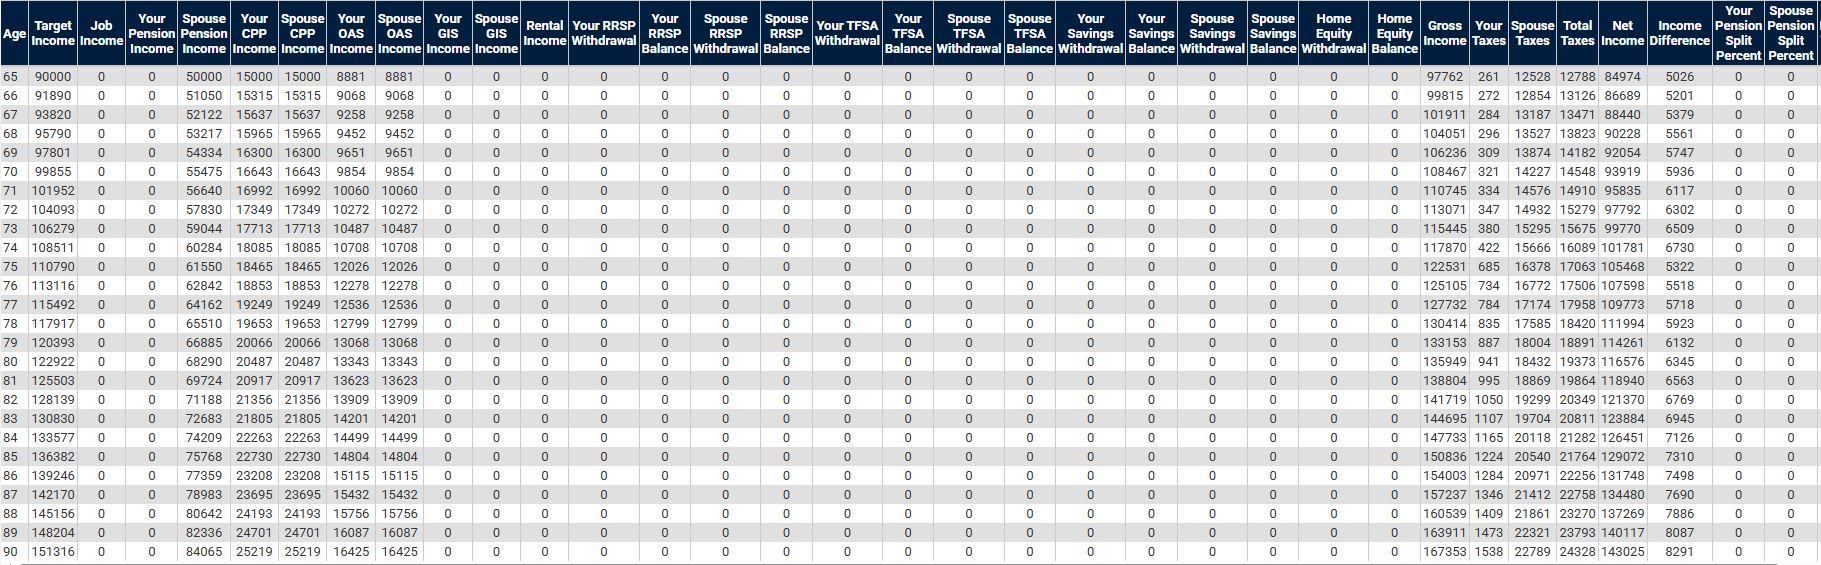
In this example, the couple reaches approximately 94% of their $90,000 after-tax target. The difference is largely related to the amount of tax generated by the income concentrated in the higher-income spouse's tax return.
This is where looking only at gross retirement income can be misleading. Two couples can have exactly the same amount of household income but very different after-tax cash flow depending on how that income is distributed.
Scenario 2: With Pension Income Splitting
Next, we modeled the same couple with eligible pension income being allocated between the spouses.
The goal isn't necessarily to split exactly 50%. The most tax-efficient percentage can vary from one household to another. A good retirement calculator can test different percentages and incorporate the resulting changes into the broader retirement plan.
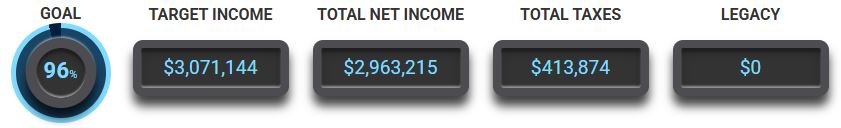
Summary Dashboard — With Splitting
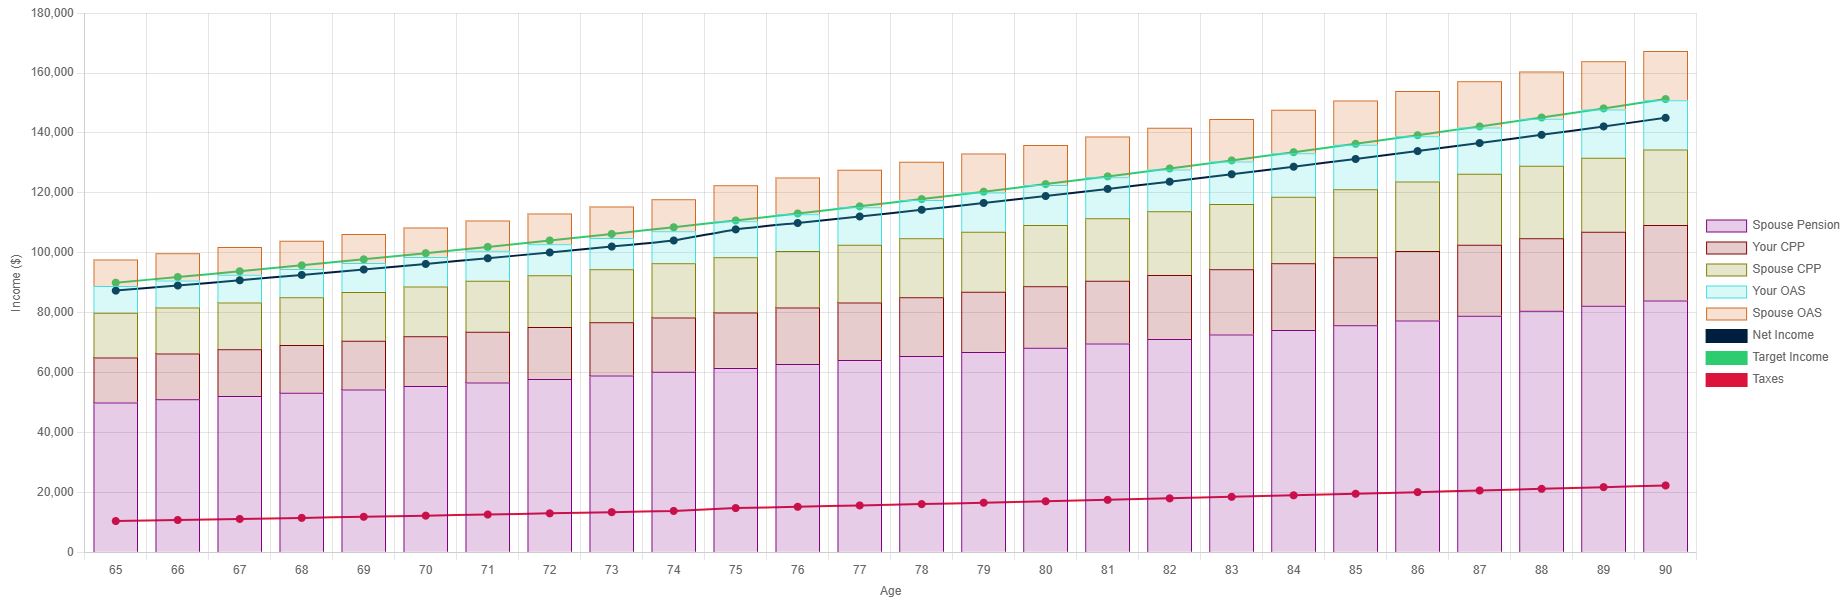
Yearly Income Chart — With Splitting
Detailed Breakdown Table — With Splitting
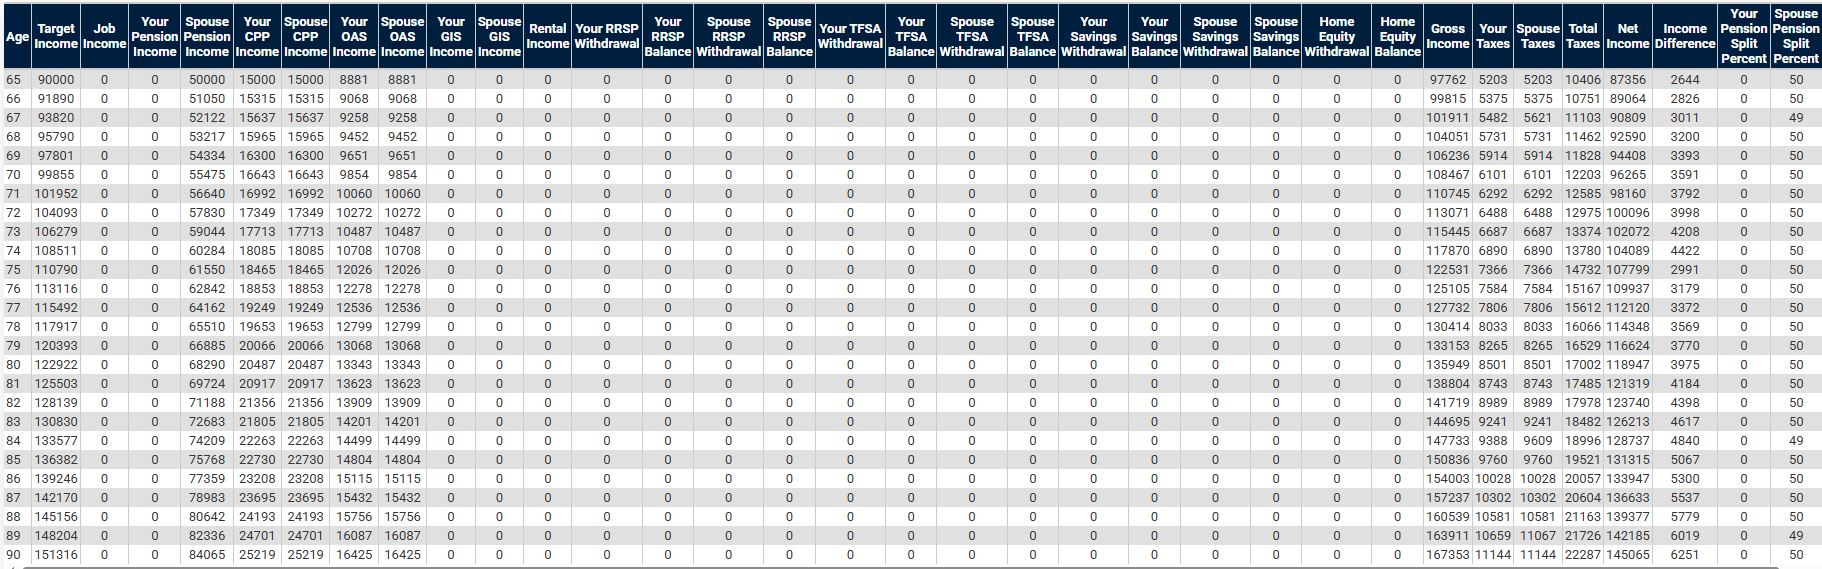
With income splitting included in this particular Retirementize scenario, the couple reaches approximately 96% of their retirement income target.
The model showed approximately $2,382 in annual tax savings in today's dollars compared with the same scenario without splitting. Over a 25-year planning period, simply multiplying that amount by 25 would produce almost $60,000, although that should not be interpreted as a guaranteed lifetime saving. Actual savings can change from year to year as income, tax brackets, government benefits, inflation and other assumptions change.
Why the Difference Can Be Significant
Canada's income tax system is progressive. As taxable income rises, additional income can be subject to higher marginal tax rates.
Consider a simplified example. Suppose one spouse has considerably more eligible pension income while the other spouse has relatively little taxable income. Without splitting, much of the household's taxable pension income may be reported by the higher-income spouse.
If some eligible pension income is allocated to the lower-income spouse, the couple may be able to use the lower-income spouse's available tax brackets and certain individual credits more effectively.
The result isn't always a large tax reduction. In some households, the difference may be relatively small. In others, the effect can be meaningful. The only reliable way to know is to model the household's actual income sources and tax situation.
Income Splitting Can Affect More Than Income Tax
One reason retirement calculations can become complicated is that taxable income can affect more than the amount of income tax you pay.
The CRA notes that pension income splitting can affect benefits and credits calculated using an individual's net income. This can include certain age amounts, spouse or common-law partner amounts and the repayment of OAS benefits.
As a result, simply comparing the two spouses' marginal tax rates isn't always enough. A comprehensive retirement model should consider the broader effect of the income allocation.
What About CPP and OAS?
This is a common source of confusion.
CPP
CPP benefits are not eligible for the CRA pension income splitting election. However, couples may be able to use CPP pension sharing, which is a separate program administered through Service Canada.
Where both spouses have contributed to CPP, pension sharing can distribute portions of the CPP retirement pensions between them under the applicable rules. The combined amount of the two pensions does not increase as a result of pension sharing.
OAS
OAS is also not eligible for the CRA pension income splitting election. Therefore, a retirement calculator should not simply take a couple's combined OAS and move half of it from one spouse to the other as though it were eligible pension income.
This distinction is particularly important when analyzing OAS recovery tax, commonly called the OAS clawback.
Why a Retirement Calculator Needs to Model Taxes
A basic retirement calculator might ask how much you have saved and estimate how long that money will last. That's useful, but it doesn't tell the whole story.
Canadian retirees can have income from many different sources:
- Employer pensions
- CPP
- OAS
- RRSP withdrawals
- RRIF withdrawals
- TFSA withdrawals
- Non-registered investments
- Rental income
- Part-time employment
- Other retirement income
These sources don't all receive the same tax treatment. Some are taxable, some aren't, and some can be subject to different rules for income splitting.
That's why an after-tax retirement income target can be much more useful than simply asking, "How much income will I have?"
How to Test Income Splitting in Your Own Retirement Plan
If you're a Canadian couple approaching retirement, consider running at least two versions of your retirement plan:
- Run the plan without income splitting. This gives you a baseline for taxes and after-tax income.
- Identify which income is eligible to be split. Don't assume every pension or government benefit qualifies.
- Test different splitting percentages. The maximum 50% isn't automatically the optimal percentage.
- Compare after-tax household income. Look beyond gross income.
- Check government benefits. Changes in individual net income can affect certain credits and benefits.
- Run the plan over multiple years. Your income mix can change substantially as you move from age 65 into later retirement.
What This Means for Our Example Couple
In this case study, the couple's retirement plan improved when eligible pension income was split between them. Their modeled after-tax income moved from approximately 94% of their target to 96%, while the model showed approximately $2,382 less tax in today's dollars.
The important lesson isn't that every couple will save $2,382. It is that the way retirement income is distributed between spouses can matter almost as much as the total amount of income.
A couple with two similar pensions may see relatively little benefit from splitting. A couple where one spouse has a large pension and the other has comparatively little taxable income may have a very different result.
Don't Stop at the First Retirement Calculation
Retirement planning is not a one-number exercise. You can change one assumption and produce a very different result.
Try changing:
- Your retirement age
- Your after-tax spending target
- Inflation
- Investment returns
- Pension income
- CPP and OAS start dates
- RRSP and RRIF withdrawals
- TFSA withdrawals
- Income splitting percentages
- Your planning age
The goal is not to find one "perfect" retirement number. It's to understand how your retirement plan behaves when real-life circumstances change.
Conclusion
Pension income splitting is one of the tax-planning tools Canadian couples should consider when building a retirement income strategy. When eligible pension income is concentrated in one spouse's name, allocating some of that income to the other spouse can sometimes reduce the family's combined tax bill and increase after-tax cash flow.
But the details matter. CPP and OAS are not eligible for CRA pension income splitting, although CPP has a separate pension-sharing program. RRIF and other pension income may qualify depending on the applicable rules and circumstances.
That's why a retirement calculator should do more than project investment growth. It should help you see the interaction between income, taxes, government benefits, inflation and spending.
In our Retirementize example, income splitting improved the modeled result by reducing annual taxes and moving the couple closer to their $90,000 after-tax retirement income target.
Your result could be very different. The best place to start is with your own numbers.
